
J29DB03
Well-Known Member
The last thing you needed was the ability to add more burbles.Committed. 45% off a down pipe and 15% off MHD super licence took me over the edge.
Femto for 2025.
The last thing you needed was the ability to add more burbles.Committed. 45% off a down pipe and 15% off MHD super licence took me over the edge.
Femto for 2025.
? Going to change my username to ObnoxiousAF.The last thing you needed was the ability to add more burbles.
And the ability to turn them off completely.The last thing you needed was the ability to add more burbles.

Now THAT I’m jealous of…And the ability to turn them off completely.
And the ability to turn them off completely.
Now THAT I’m jealous of…


I wouldn't say completely.And the ability to turn them off completely.



The downshift pops are gone when I set mine to OFF, but the low gurgles when coming to a stop from like 5mph are still there.I wouldn't say completely.
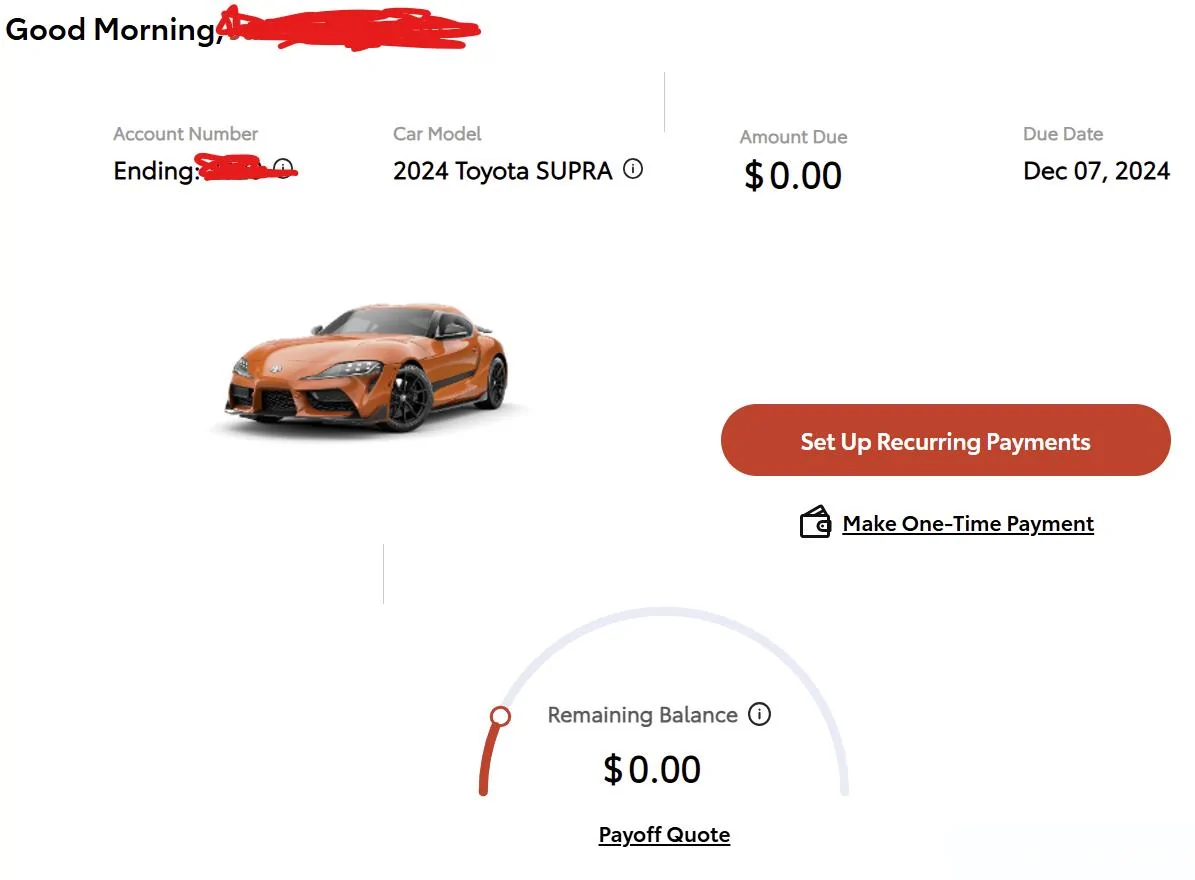
If you pulled money from a regular checking or very low yield savings account then good choice. If you liquidated an investment, even if earning less than the rate you were paying on the Supra, then it was likely not the best choice. Interest on a car loan is applied to a decreasing balance while investment yields are on increasing balances (generally). In most cases you end up earning more in your investment accounts than you pay in interest over the course of a car loan. I used to do F&I and could literally show people the math of how at the end of a 5 year car loan at say 7% the customer would have more net money if they kept their 5% 5 year CD instead of cashing it in and paying cash for their car. Probably 80% of customers couldn’t grasp the concept and cashed in the CD/other investments to pay cash, some actually accused me of lying, and only a small handful were like damn, you’re right, thanks for showing me this. Of course, this assumes you can afford the payment from current income but if you can’t you likely aren’t getting approved for a loan anyway.Decided to the pay the car off. Over the course of the year I've "owned" the car, the interest being paid just felt criminal so I decided to pull some money out and just get rid of this burden of a monthly payment. Freedom feels great. Happy thanksgiving yall.

I've had them occur when going downhill in cruise control and it would pop uncontrollable like popcorn. Something about it being barely on throttle it didn't like. Also still have them occur on track when letting off throttle a little. But yes like 99% gone.The downshift pops are gone when I set mine to OFF, but the low gurgles when coming to a stop from like 5mph are still there.
I usually leave a years worth of cash in a high yield savings, so I used a portion of that to pay the car off. Didn't touch investments or retirementIf you pulled money from a regular checking or very low yield savings account then good choice. If you liquidated an investment, even if earning less than the rate you were paying on the Supra, then it was likely not the best choice. Interest on a car loan is applied to a decreasing balance while investment yields are on increasing balances (generally). In most cases you end up earning more in your investment accounts than you pay in interest over the course of a car loan. I used to do F&I and could literally show people the math of how at the end of a 5 year car loan at say 7% the customer would have more net money if they kept their 5% 5 year CD instead of cashing it in and paying cash for their car. Probably 80% of customers couldn’t grasp the concept and cashed in the CD/other investments to pay cash, some actually accused me of lying, and only a small handful were like damn, you’re right, thanks for showing me this. Of course, this assumes you can afford the payment from current income but if you can’t you likely aren’t getting approved for a loan anyway.
 I have good credit, but the addition of the car added to my debt/income ratio so my interest on the car wasn't favorable at all. I obviously need to build the savings back up to a comfortable cushion again, but that's ok. Good advice all around though!
ditto. title in hand. love having no payments.Decided to the pay the car off. Over the course of the year I've "owned" the car, the interest being paid just felt criminal so I decided to pull some money out and just get rid of this burden of a monthly payment. Freedom feels great. Happy thanksgiving yall.
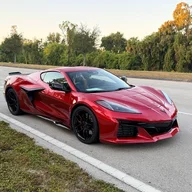
I’m sure you see the worst of the worst at car dealerships. Hopefully most guys “buying” Supras can afford them in the 1st place. Like Randall & Andrew, I paid mine off as well. Knowing this is a depreciating asset, using cash reserves is likely more common.If you pulled money from a regular checking or very low yield savings account then good choice. If you liquidated an investment, even if earning less than the rate you were paying on the Supra, then it was likely not the best choice. Interest on a car loan is applied to a decreasing balance while investment yields are on increasing balances (generally). In most cases you end up earning more in your investment accounts than you pay in interest over the course of a car loan. I used to do F&I and could literally show people the math of how at the end of a 5 year car loan at say 7% the customer would have more net money if they kept their 5% 5 year CD instead of cashing it in and paying cash for their car. Probably 80% of customers couldn’t grasp the concept and cashed in the CD/other investments to pay cash, some actually accused me of lying, and only a small handful were like damn, you’re right, thanks for showing me this. Of course, this assumes you can afford the payment from current income but if you can’t you likely aren’t getting approved for a loan anyway.


Considering the xHP also. Would love to hear your take once installed.I’m sure you see the worst of the worst at car dealerships. Hopefully most guys “buying” Supras can afford them in the 1st place. Like Randall & Andrew, I paid mine off as well. Knowing this is a depreciating asset, using cash reserves is likely more common.
Since CDs have prepayment penalties, they are not considered fully liquid. So you’re right in that aspect if that was their only choice. However, if a client moved one of their cash investments into a CD, in anticipation of purchasing a car at the maturity date, then that would make a more sense.
At some point in life, your liabilities (other than primary residence) shouldn’t be tied up in any loan, paying interest to a bank. You loose the ability to invest in other opportunities. That’s why we all have emergency funds (3, 6, 12 months of income) and fully liquid cash investments that is a percentage of our net worth. That should be part of anyone’s portfolio.
Oh yeah…. I bought the xHP transmission tune, downloaded the app, went to get the software code and realized my car is at the auto spa ? again getting some minor adjustments for her next track weekend ??